Your first home: what you can buy
Where we're up to
Thanks for sending your payslips, contract, HELP statement and spending summary. I've rerun your numbers on those documents, so this page replaces the estimates in my first eMail.
Your documents came out a little better than my estimate. Your base salary is $152,076, up from the $145,000 I'd worked back from your take-home pay. Your HELP balance is $164,401, a bit higher than we thought, and that takes some of the gain back. This is still not an application, and nothing has touched your credit file.
Try a price
Move the slider to any price you're looking at. Everything below updates: the cash you'd need, the loan, and how many of the lenders on the 5% scheme would lend you that much.
Cash you'd need
Your loan
- The most each lender will lend you today
- The loan you'd need at this price
Your month after you buy
Your board stops once you move out, so I've taken your September spending without the $1,200 you pay at home, and added the loan and the running costs of owning a place.
Your allowances come on top of this. Duty hours, communications and the RDO allowance added between $416 and $1,499 a fortnight in your last two payslips.
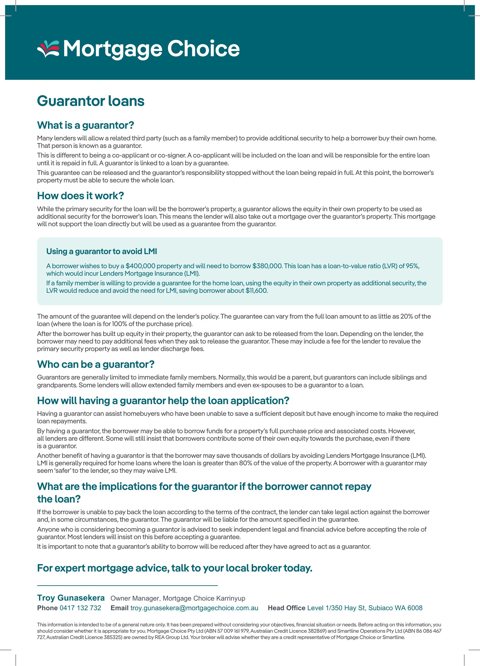
Would a guarantor help?
- What a guarantor does. A parent offers some of the equity in their home as extra security for part of your loan. It lets you borrow up to the full price without paying Lenders Mortgage Insurance (LMI).
- Why it doesn't lift your borrowing. Lenders still set the size of the loan from your income and your spending. A guarantee adds security, not income, so the figures on this page stay the same.
- Why you don't need one now. The 5% scheme already lets you buy with a 5% deposit and no LMI. The two do the same job, so you'd use one or the other, and the scheme doesn't put your parents' home on the line.
- When one could help later. If you wanted to keep more of your own cash, or buy above the scheme's $850,000 price cap for Perth.
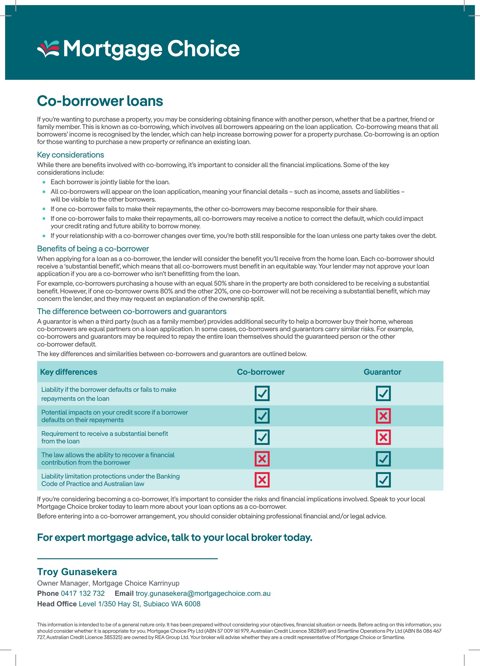
- What does lift borrowing: more income on the loan. If Amber joins once she's working full time, both incomes count, and if she's also a first home buyer the scheme still applies. Your parents could join as borrowers, but they'd take on the debt with you, and because they already own a home it would take the 5% scheme off the table.
What could lift your number
- Finishing probation. Your six months end around 8 December 2026. Some lenders are more comfortable once that's done, and it lines up well with buying early next year.
- Your allowances. I've left them out. With a longer run of payslips, some lenders will count regular allowances, which would add to your borrowing.
- Your next pay step. Your contract has you on the Year 1 First Officer rate. When it steps up, send me the letter and I'll rerun the numbers.
- Amber. A second income is the biggest lever, as above.
- Interest rates. A fall in rates lifts everyone's borrowing, and a rise works the other way.
Fact sheets for you
Three short Mortgage Choice fact sheets that go with your questions. Each one opens in a new tab, and you can download it from there.
Next steps
- Coffee. Sorry I missed the 14th. I'm free on the mornings of Friday 23 October and Monday 26 October, or tell me what suits your roster.
- When you're ready to go further: the last three months of statements for your savings account and your ETF holdings.
- When you see a place you like, send me the address and I'll run a property report, so you know what it's worth before you make an offer.
How these figures work: your base salary of $152,076 from your contract and payslips, your HELP balance of $164,401 from your statement, and your September spending of $3,256 a month without board. Allowances are not counted. Borrowing was assessed on 19 October 2026 across the lenders I work with; only lenders on the Housing Australia panel for the 5% Deposit Scheme are shown. Repayments use 6.6% a year, principal and interest over 30 years; the rate you're offered may differ. Stamp duty uses the first home buyer rate for an established home in WA, and other costs are estimated at $3,600. Running costs of $400 a month are an estimate. This page gives general information only and is not an approval or an offer of credit.